

Applying for a surety bond is an important step for many contractors, business owners, and professionals. While the process is often straightforward, not every application receives immediate approval. A denial does not always mean you cannot obtain a bond in the future. In many cases, it simply means the surety company needs greater confidence in your financial stability, business experience, or ability to fulfill your obligations. Understanding the common reasons behind a denial can help you take practical steps toward approval. Businesses seeking guidance often work with Quantum Insurance Services to better understand the bonding process and prepare stronger applications that meet surety underwriting requirements.
What Is a Surety Bond?
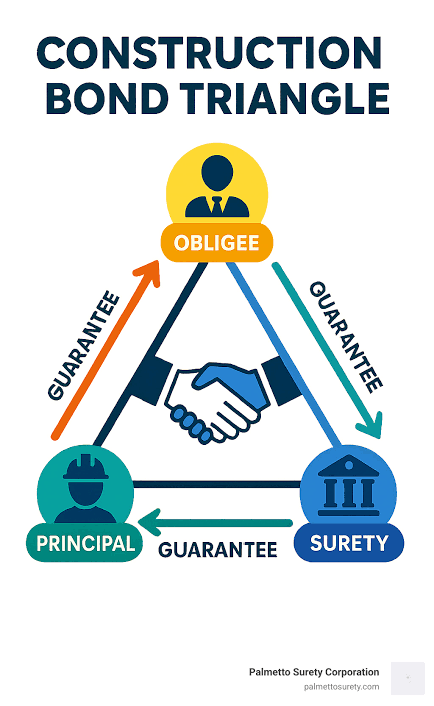
A surety bond is a three-party agreement involving:
The Principal: The individual or business required to obtain the bond.
The Obligee: The organization or government entity requiring the bond.
The Surety: The company that issues the bond and guarantees the principal will meet the required obligations.
Unlike traditional insurance, a surety bond is a financial guarantee that protects the obligee if the bonded party fails to fulfill contractual or legal responsibilities.
Common Reasons a Surety Bond Application Gets Denied
Understanding why applications are declined is the first step toward improving your chances of approval.
1. Poor Credit History
One of the most common reasons for denial is a low credit score or negative credit history. Surety companies often review personal and business credit to evaluate financial responsibility.
Factors that may raise concerns include:
Missed loan payments
Collections or judgments
High credit utilization
Recent bankruptcies
Multiple delinquent accounts
While poor credit does not always make bonding impossible, it may increase underwriting scrutiny.
2. Weak Financial Statements
Sureties evaluate financial strength because they want confidence that the applicant can fulfill contractual obligations.
Financial concerns may include:
Low cash reserves
Negative working capital
Excessive debt
Declining revenue
Limited business assets
Incomplete or outdated financial statements can also make approval more difficult.
3. Lack of Industry Experience
For contract bonds, experience matters. A surety wants evidence that the contractor or business has successfully completed similar work.
Potential concerns include:
New business with limited operating history
No record of comparable projects
Inexperienced management team
Rapid expansion into unfamiliar work
Experience helps demonstrate the ability to complete obligations successfully.
4. Previous Bond Claims
A history of claims against previous bonds can signal increased risk.
Sureties may carefully evaluate:
Frequency of claims
Cause of claims
Whether financial losses occurred
Steps taken to prevent future issues
Past claims do not always result in denial, but they often require additional explanation.
5. Incomplete Application Information
Simple paperwork errors can delay or prevent approval.
Examples include:
Missing financial documents
Incorrect business information
Incomplete project details
Missing signatures
Inaccurate licensing information
Providing complete and accurate documentation helps underwriters make informed decisions.
6. Large Bond Amount Relative to Business Size
If the requested bond amount is significantly larger than the company's financial capacity or operating history, the surety may determine that the risk is too high.
This is particularly common when businesses pursue contracts that exceed their current capabilities.
How to Improve Your Chances of Approval
A denial is often an opportunity to strengthen your application before reapplying.
Improve Your Credit
Building stronger credit can increase underwriting confidence.
Helpful strategies include:
Paying bills on time
Reducing outstanding debt
Correcting credit report errors
Avoiding unnecessary new credit accounts
Even modest improvements can positively influence future applications.
Strengthen Financial Records
Organized financial documentation demonstrates responsible business management.
Consider maintaining:
Current balance sheets
Income statements
Cash flow reports
Business tax returns
Bank references
Professional financial statements prepared by an accountant may also support your application.
Build a Strong Project History
Businesses can gradually establish credibility by successfully completing smaller projects before pursuing larger contracts.
Keeping records of completed work, client references, and project performance can strengthen future bond applications.
Address Previous Financial Issues
If your business experienced temporary financial challenges, be prepared to explain:
What caused the issue
How it was resolved
What improvements have been made
Why the situation is unlikely to recur
Clear documentation often provides valuable context for underwriters.
Submit Complete Documentation
Carefully review every application before submission.
Verify that:
All required forms are complete
Financial documents are current
Business information is accurate
Supporting documentation is included
Well-prepared applications reduce unnecessary delays.
Can You Reapply After Being Denied?
Yes. Many applicants successfully obtain bonds after improving their financial position or providing additional information.
Depending on the reason for denial, you may benefit from:
Improving your credit profile
Increasing working capital
Providing updated financial statements
Demonstrating additional business experience
Correcting incomplete documentation
The appropriate timeline for reapplying depends on the specific underwriting concerns identified during the initial review.
When Professional Guidance Can Help
Surety underwriting can involve financial analysis, project evaluation, and documentation requirements that vary depending on the bond type and project size. Working with an experienced insurance agency can help applicants understand what underwriters typically review, identify potential concerns before submitting an application, and ensure that all required documentation is complete.
Conclusion
A denied surety bond application is not necessarily the end of the process. Credit concerns, financial strength, limited experience, incomplete paperwork, or previous claims are among the most common reasons applications are declined. Fortunately, many of these issues can be addressed through better financial management, stronger documentation, and careful preparation. By understanding what sureties evaluate and taking proactive steps to improve your application, businesses can increase their chances of obtaining the bond they need and move forward with greater confidence.

Write a comment ...